How Home Appraisals Work: Value, Low Appraisals & Next Steps
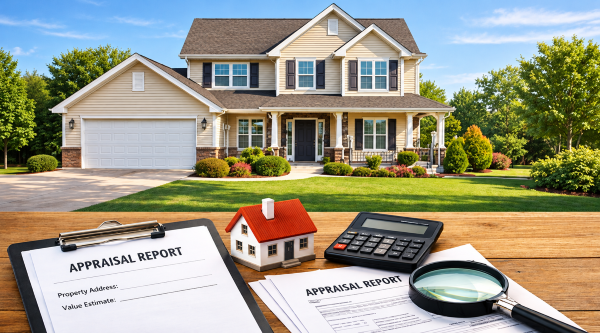
Home appraisals sit right in the middle of the deal—between what buyers hope for, what sellers expect, and what lenders are willing to fund. When the number comes in where everyone expects, the process feels invisible. When it doesn’t, the appraisal suddenly becomes the most important page in the file. This guide walks buyers and sellers through how home appraisals work, what shapes value, and what to do when the number comes in lower than planned.
At a Glance: Why the Appraisal Matters
For buyers, the appraisal is the moment when the lender decides how much they’re willing to lend against the home. For sellers, it’s the outside opinion that either supports the price or forces a hard look at the numbers. The appraised value becomes the anchor for the loan-to-value ratio, the financing structure, and sometimes the renegotiation that follows. A clear understanding of how this number is built makes the mortgage math feel lighter and the next steps more manageable.
What Is an Appraisal?
A home appraisal is an independent, licensed appraiser’s estimate of a property’s current market value. The appraiser reviews the home’s size, layout, condition, features, and location, then compares it to recent nearby sales. Lenders order the appraisal to protect their risk; buyers and sellers use it as a reality check on price. It’s not a guarantee of what the home will sell for in the future—it’s a snapshot of what similar homes are selling for right now, under current market conditions.
What the Appraiser Actually Does
During the visit, the appraiser measures rooms, notes upgrades and wear, takes photos, and looks at how the home fits into the neighborhood. Afterward, they select comparable sales, adjust for differences, and arrive at a value range. The final number is not personal; it’s the result of a structured process. Understanding that process helps both buyers and sellers respond calmly if the value doesn’t match the contract price.
Low Appraisal Issues: When the Number Falls Short
A “low appraisal” happens when the appraised value comes in below the price buyers and sellers agreed to in the contract. Because lenders base the loan amount on the lower of the purchase price or appraised value, a gap opens between what the buyer planned to borrow and what the lender will actually fund. That gap has to be solved with price changes, extra cash, or a different plan.
Options for Buyers and Sellers
Buyers can ask the seller to reduce the price, split or cover the difference in cash, or request a formal reconsideration of value if the comps seem off. Sellers can agree to a lower price, challenge the appraisal with better data, or look for a cash buyer whose offer isn’t tied to a lender’s appraisal. The key is treating a low appraisal as a live problem with specific options—not as an automatic deal-killer.
Talking to the Appraiser (Before and After)
Most buyers and sellers never speak directly with the appraiser, but thoughtful communication—through your agent and lender—can help. Before the visit, your agent can provide a clean list of recent comparable sales, highlight upgrades, and clarify any unique features that affect value. After the report, if something seems off, your agent can work with the lender to request a reconsideration using stronger comps or corrected property details.
What Helps, What Doesn’t
What helps is organized information: documented improvements, accurate square footage, and relevant nearby sales. What doesn’t help is pressure, emotion, or arguing about what the home “should” be worth. Appraisers work inside guidelines; the best move is to give them clear, factual data that supports the value you believe is fair.
Who the Appraisal Really Protects
On paper, the appraisal protects the lender by making sure the property is worth enough to secure the loan. In practice, it also protects buyers from overpaying in fast-moving or overheated markets. For sellers, a strong appraisal can validate the price and give buyers confidence in the deal. When the number is lower than expected, it’s frustrating—but it’s also a signal that the market may not fully support the contract price.
Seeing It as a Safety Check
Thinking of the appraisal as a safety check rather than a judgment can change the tone of the conversation. Buyers gain a clearer picture of value; sellers see how the market is reading their home. That perspective makes it easier to negotiate from facts instead of feelings.
How Value Is Determined
Appraisers lean heavily on comparable sales—recent, nearby properties similar in size, age, and condition. They adjust up or down for differences like extra bathrooms, finished basements, larger lots, views, or significant upgrades. Condition matters: deferred maintenance, outdated systems, or visible issues can pull value down, while well-documented improvements can support a higher number.
Market Conditions and Timing
Value isn’t just about the house; it’s about the market around it. In rising markets, contract prices can move faster than the comps, increasing the risk of low appraisals. In cooling markets, appraisals may land below recent aggressive offers. Understanding where your local market sits—steady, rising, or softening—helps buyers and sellers anticipate how the appraisal might come in and plan their strategy.
Appraisal vs. Inspection: Two Different Checkpoints
An appraisal answers one question: “What is this home worth in today’s market?” An inspection answers another: “What is the condition of this home, and what issues might need attention?” The appraiser is focused on value and marketability; the inspector is focused on systems, safety, and repairs. Both matter, but they serve different roles in the buying and selling journey.
How They Work Together
For buyers, the inspection often drives repair requests, while the appraisal shapes financing and price discussions. For sellers, a clean inspection and a solid appraisal together create a smoother path to closing. Seeing them as complementary checkpoints—not overlapping ones—helps keep expectations realistic.
How to Prepare for the Appraisal
Buyers don’t control the property, but they can work with their agent and lender to make sure the appraiser has clean information. Sellers can do a bit more: tidy the home, handle obvious minor repairs, gather documentation for upgrades, and make sure access is easy and the property shows its true condition. None of this guarantees a higher value, but it reduces the chance that small, fixable issues drag the number down.
Practical Prep for Buyers and Sellers
For sellers, think in terms of clarity: clear paths, working lights, visible improvements, and a simple list of upgrades with dates and costs. For buyers, focus on understanding how the appraisal fits into your loan approval, so you’re ready to respond if the number comes in higher, lower, or right on target. The more you understand the process, the less heavy the appraisal feels when it arrives.
Real Estate Appraisals FAQ
Who pays for the appraisal?
Usually the buyer, even though the lender orders it as part of the financing process.
Do cash buyers need an appraisal?
No, but many still choose to get one for peace of mind and stronger negotiation positioning.
Can a low appraisal be challenged?
Yes—especially when supported by better comparable sales data or corrected property details.
Does a high appraisal help the seller?
It can support the price, but the buyer often benefits most by gaining instant equity.
How long does an appraisal take?
The on-site visit typically takes 30–120 minutes, while the full report may take several days to a week.
Can repairs affect the final appraised value?
Yes. Even small improvements can influence how an appraiser views condition and overall marketability. If you’re planning updates, this home improvement contract checklist helps you organize the work so everything is documented clearly.
Do first-time buyers need to prepare differently for an appraisal?
Not necessarily, but understanding what appraisers look for can make the process feel lighter. If you’re new to the buying journey, this guide for first-time home buyers explains the steps that lead up to the appraisal and how it fits into your loan approval.
Strategic Pages To Read Next
These quick-reference guides help buyers, sellers, and agents move through the appraisal process with clearer footing:
- How 2026’s market direction shapes value, leverage, and next steps
- The cost breakdown that strengthens negotiations after an appraisal
- How easements influence use, value, and the appraiser’s final number
Additional Articles for Buyers and Sellers Comparing Value & Pricing
Understanding the appraisal is one step—knowing what to do next is where deals are won or lost. These guides help you move forward with confidence.
Home > Real Estate Articles >> Real Estate Articles For Buyers and Sellers >> How Home Appraisals Work
🔥Top Pages in September 2026
💌 Expired Listing Letters →
Send the message that gets sellers calling you back
🏷️ Real Estate Agent Directory →
Get discovered by buyers, sellers, and referral partners searching for agents
📝 Email Marketing for Real Estate Agents →
Send emails that spark replies and start real conversations
🏷️Real Estate Marketing Talk Blog →
Get fresh ideas that help agents grow, connect, and win more business
📬Real Estate Website Content →
Simple System. Uncommon Results.
🚪 Your Gateway to Targeted Insights
👔 For Agents →
Branding tips, lead gen strategies & marketing tools to grow your business
🏡 For Buyers → Smart buying guides, market insights & negotiation tips for your next move
📦 For Sellers → Listing prep, pricing strategies & proven tactics to sell fast and profitably
💰 For Investors → ROI-focused content, property analysis tools & market trend breakdowns